

Get Paid Early: Cash Advance
4.2

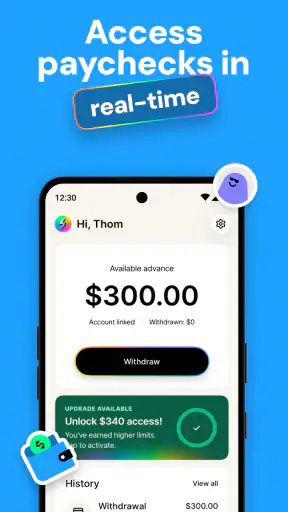
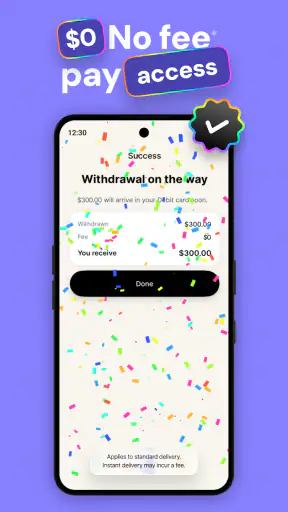
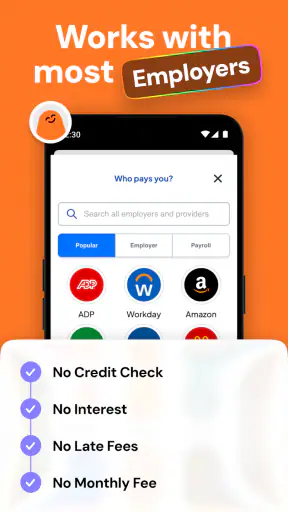
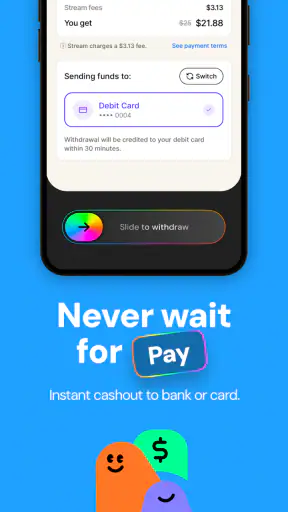
I approached Get Paid Early: Cash Advance as a practical finance app rather than a general budgeting tool. Its purpose is straightforward: help eligible users access money they have already earned before their normal payday, without presenting the service as a traditional loan. That distinction matters, because the app is most useful when a timing problem is temporary, not when someone needs a long-term solution for an income shortfall.
After spending time with it, my view is that this is a focused tool for smoothing out awkward gaps between an incoming paycheck and an urgent bill. The experience is built around speed and simplicity, but that simplicity also means I would not use it as a replacement for a full banking app, a detailed spending tracker, or a proper emergency fund. It works best when I treat it as one small part of my financial routine.
How the everyday workflow feels
The basic routine is easy to understand. I open the app, review what is available, request access to earned pay when needed, and then plan around the next regular payday. The important mental shift is that this is not extra income. It is money arriving earlier than usual, so I still have to account for the smaller amount that may be left for the normal pay cycle.
That makes the first useful habit surprisingly simple: I check the request against my upcoming obligations before accepting it. If a utility payment is due before payday, an early-pay option can be helpful. If I am using it to cover ordinary spending every week, the convenience can hide a recurring cash-flow problem. I found the app easier to judge when I treated every request as a timing decision rather than as available spending money.
The app comes from StreamFunds, Inc. and sits clearly in the finance category. It is free to install and carries an Everyone age rating, which makes the initial barrier low. The current release is version 3.0.39, and the minimum operating-system requirement is Android 7.0. On compatible devices, that broad support is useful for people who do not own a recent phone.
One practical question many people will have is whether this is the same as taking out a payday loan. The service is presented around accessing earned pay, with no loans, no interest, and no hidden fees in its store summary. I still recommend reading each screen carefully before confirming a transaction, especially any explanation of timing or eligibility. “No interest” does not mean that every financial situation becomes harmless; receiving pay early can still leave the next pay period tighter.
A realistic example is a worker whose paycheck normally arrives at the end of the week, while a necessary household bill is due a couple of days earlier. Instead of waiting and risking a late payment, that person may use the app to bridge the short gap. The sensible follow-up is to reduce discretionary spending until payday, because the early access changes timing, not the total amount earned.
The first setup deserves patience
I would not rush through the initial screens. Finance apps need enough information to determine whether their service can work for a particular user, and the usefulness of this one depends on that connection between employment income and the app’s eligibility process. If the setup feels inconvenient, it is better to stop and understand what is being requested than to approve everything automatically.
I also recommend checking the destination for any money before making a request. An early-pay service is only useful if the funds arrive where I expect them and at a time that matches the bill I am trying to cover. A request made without checking those details can create a different problem: the money may be technically available but not convenient for the payment that prompted the request.
Another point is eligibility. The app’s concept may sound universal, but earned-pay access depends on the user’s circumstances and the information available to the service. I would not install it assuming that every employer, pay schedule, or work arrangement will behave the same way. People with irregular freelance income, cash wages, or several unrelated income sources may find a conventional bank account or budgeting method more predictable.
Settings and habits worth checking
There is no reason to open a finance app only when a bill is already overdue. I prefer checking its account and notification settings during a calm moment, then deciding which alerts are genuinely useful. A reminder about an important status change can prevent repeated manual checking, while too many notifications can turn a financial tool into background noise.
I would also review the app after changing jobs, switching pay schedules, or moving to a different bank account. Information that was correct during setup may no longer reflect the way income arrives. This is one of the less obvious maintenance tasks with an earned-pay service: the app’s usefulness depends on current payroll circumstances, not simply on having the application installed.
Privacy deserves attention as well. Before connecting financial or employment information, I read the permission explanations and consider whether the convenience is worth the information exchange for my situation. I would never share login details through a message or unofficial form claiming to represent the app. Keeping the application updated through the normal platform store is also a sensible security habit, particularly for a finance product.
The app is free, which removes the usual download-cost question, but I still separate “free to install” from “free of responsibility.” I keep a small note of any early-pay request and the reason for it. That record makes it much easier to notice whether I am solving occasional timing issues or quietly depending on early access to make the whole month work.
Faster patterns for repeat users
Experienced users can make the process less stressful by creating a repeatable check before every request. Mine would be: confirm the amount needed, confirm the bill date, check the next paycheck, and decide what spending must wait. This takes less time than reacting to a rejected payment or discovering that an early request has made the next pay period uncomfortable.
A second useful pattern is to use the app for specific, named purposes instead of vague spending. “Cover the electricity bill due Wednesday” is a controlled decision. “I have money available, so I can spend more today” is not. Naming the purpose creates a natural stopping point and reduces the chance that convenience becomes a habit.
I also prefer handling requests during normal daytime hours rather than at the last possible moment. That is not a promise about processing speed; it is simply better planning. If anything needs attention, I have time to review the screen, check my bank balance, and choose another payment arrangement. Relying on an early-pay request minutes before a deadline leaves no room for an unexpected issue.
For users who receive income on a regular cycle, a calendar reminder can work alongside the app. I can mark the expected payday, the dates of major bills, and a short review point before requesting access. This turns the application from an emergency button into part of a broader cash-flow routine. The app handles the early-pay question, while the calendar handles the bigger picture.
One trade-off is that speed can encourage less reflection. Traditional banking usually makes me wait for a transfer or plan around a fixed payday, which is inconvenient but naturally creates a pause. Here, the easier access means I have to provide that pause myself. I consider this the central discipline required to use the product well.
Where the limits become important
The biggest limitation is scope. This is not the app I would choose for building a complete monthly budget, tracking every category of spending, comparing savings goals, or managing investments. Someone who wants a detailed view of household finances will probably be better served by a dedicated budgeting app or the tools inside a full-service bank.
I would also skip it if my income is too unpredictable for earned-pay access to be meaningful. A person paid irregularly may need a larger emergency reserve, a flexible savings system, or direct advice from a financial professional rather than repeated early access. Likewise, anyone already using one advance to repay another should treat that pattern as a warning sign and look for a sustainable change in expenses or income.
The phrase “no loans” may make the service sound risk-free, but the timing effect still deserves respect. If I access part of my pay early, the ordinary payday may provide less room than I expect. That can lead to a cycle in which each pay period begins with money already committed. I would set a personal rule that early access is for a defined short-term need, not for routine shopping, subscriptions, or lifestyle upgrades.
There is also a practical comparison with overdraft protection. An overdraft facility may help when a payment has already reached an account with insufficient funds, while an earned-pay app is more proactive: I request access before the bill is due. Neither option fixes an underlying shortage, and the better choice depends on the timing and terms of the specific situation. I prefer planning early because it gives me more control, but I would not assume that one tool is automatically cheaper or more suitable in every case.
Compared with asking friends or family for money, the app can feel more private and structured. Compared with a credit card, it avoids turning a short gap into a revolving balance with interest. On the other hand, a credit card may offer payment flexibility that this focused service does not. My choice would depend on whether I am managing a one-time timing mismatch or carrying an expense that cannot realistically be covered by the next paycheck.
People also ask whether the app is suitable for teenagers because of its Everyone rating. I would not interpret an age label as a guarantee that every user can access a finance service. Eligibility, income, and account circumstances matter more than the general content rating. Adults should make sure they understand the service before involving another household member.
Who will get the most value
I see the strongest fit for employed users with a dependable pay cycle, a clear short-term bill, and enough income to cover normal expenses after the early request. The app can be particularly convenient when the issue is a mismatch of a few days rather than a genuinely unaffordable bill.
It may also suit someone who dislikes using credit for small emergencies and wants a direct way to think about earned income. The free installation and simple focus make it approachable, while the current user base gives it some useful social proof: it has a 4.2 average from over 700 ratings and more than 50 thousand installs. Those figures suggest real interest, but they do not replace checking whether the workflow fits my own pay arrangement.
I would be more cautious if I had unstable income, several overdue accounts, or no plan for the next pay period. In those cases, the app could make today easier while making the following week harder. A bank conversation, debt counselor, employer payroll option, or basic spending reset may be more valuable than another way to move income forward.
The app is also not a substitute for savings. Even if I use it responsibly, I would still work toward keeping a small reserve for predictable surprises. The long-term improvement comes when fewer expenses require early access, not when I become faster at requesting it.
My verdict after using it as a routine tool
Get Paid Early: Cash Advance is a focused finance app that makes sense when payday timing is the problem. I like its direct purpose, free entry point, and emphasis on accessing earned pay rather than borrowing with interest. The best experience comes from pairing it with a simple personal rule: decide the reason first, check the next payday second, and request only what solves the immediate gap.
Its limitations are just as important as its convenience. It does not replace budgeting, savings, stable income, or careful bill planning. The faster the request process feels, the more responsibility sits with me to avoid treating early access as extra money. That is the main trade-off, and it is easy to miss if I focus only on the short-term relief.
With an average rating of 4.2 across more than 700 ratings, the app has earned a generally positive reception, and its install count is above 50 thousand. I would recommend it to someone with predictable earnings who occasionally needs to bridge a small timing gap. I would not recommend building a monthly financial strategy around it, and I would choose a full budgeting or banking solution for broader money management.
My final opinion is positive but measured: use it as a controlled cash-flow tool, not as a permanent extension of your paycheck. If that distinction fits the way you manage money, it can be a useful addition to an Android finance routine. If every pay period already feels short, the most helpful next step is probably not earlier access, but a plan that addresses why the shortage keeps returning.
4.2
167.00 Reviews
Pros
- Fast access to earned wages before payday
- Simple application process with clear eligibility requirements
- No traditional credit check is typically required
- Useful for handling unexpected short-term expenses
- Repayment is usually aligned with your regular payday
Cons
- Advance limits may be too low for larger emergency costs
- Optional fees can make frequent use expensive
- Not all employers or payroll systems may be supported
- Repeated advances can make future paychecks feel smaller
- Availability and terms may vary by location and user profile


